 Written and reviewed by Dr. Vaishnavi Karmawat, B.V.Sc. & A.H., Registered Veterinary Practitioner
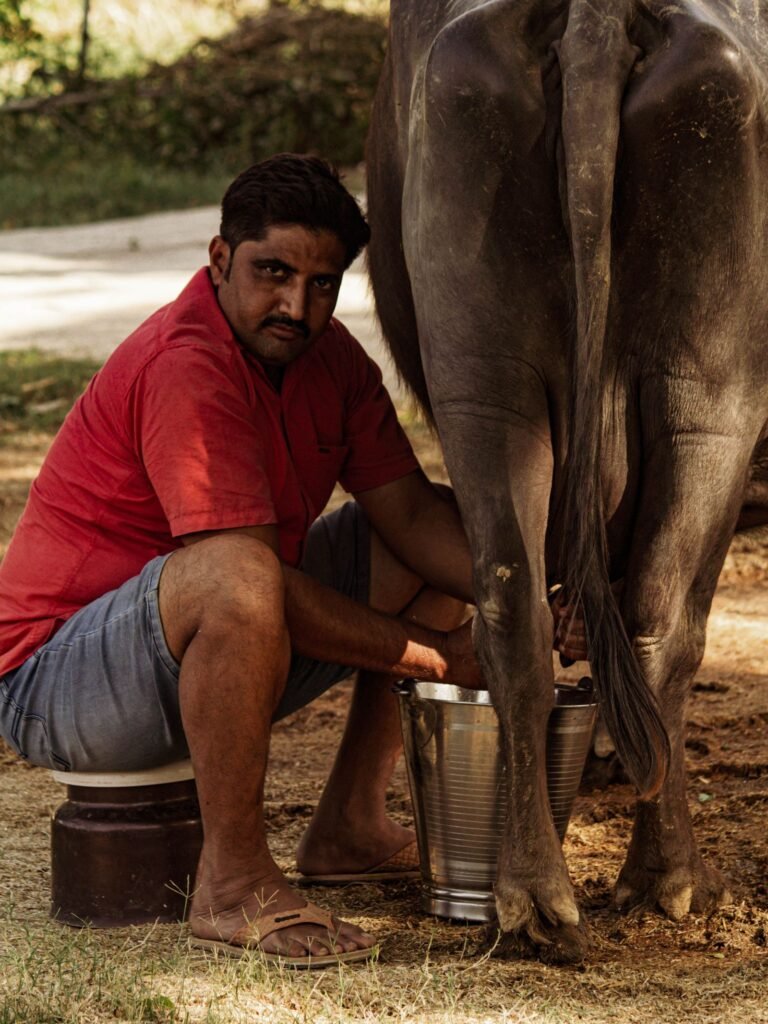
Starting or expanding a dairy farm usually needs money for animals, a shed, equipment and working capital. Many farmers try for a bank loan and get stuck on paperwork, or are rejected without understanding why. This guide explains how banks look at dairy loans, the steps to apply and how government schemes can help.
In this article
- Types of dairy finance
- How a bank looks at your dairy loan
- Step 1: Plan before you approach the bank
- Step 2: Prepare a project report
- Worked example: a 5-buffalo unit
- Step 3: Documents usually needed
- Step 4: Apply and follow up
- Step 5: Insure and tag your animals
- Why dairy loans go bad, and how to prevent it
- Tips to improve your chances
- Frequently asked questions
Key Takeaways
- Dairy finance usually combines a term loan (animals, shed, equipment) with working capital through a Kisan Credit Card for animal husbandry.
- Banks judge your repayment capacity, so a realistic project report matters more than an ambitious one.
- Budget for dry periods, calf rearing and fodder price rises; small units have thin margins after the loan instalment.
- Insure and ear-tag every animal bought with a loan, and keep a clean credit record.
- Buying healthy animals in early lactation, with a vet’s check, is the single biggest factor in repaying on time.
Bank rules, interest rates and scheme terms change. Always confirm current details with your bank and district animal husbandry office.
Types of dairy finance
- Term loan for buying animals, building sheds, buying chaff cutters, milking machines and other equipment, repaid over several years
- Working capital for feed, fodder, medicines and labour, usually through a Kisan Credit Card for animal husbandry
- Larger projects such as milk processing, chilling and feed plants may qualify for interest support under the Animal Husbandry Infrastructure Development Fund. See our dairy schemes guide.
How a bank looks at your dairy loan
- Repayment capacity: the bank compares your expected monthly surplus (milk income minus feed, labour and other costs) with the loan instalment. It wants the surplus to be comfortably higher than the instalment, not just equal to it.
- Your margin money: your own contribution, often 10% to 25% of the project cost depending on loan size and bank rules, shows commitment.
- Credit history: your CIBIL score and any unpaid loans in your name or your family’s are checked.
- Security: small agricultural loans up to the RBI collateral-free limit (₹2 lakh from January 2025) need no land mortgage; larger loans usually need security, and the animals are hypothecated to the bank.
- Experience and market: training, existing animals, and a milk buyer such as a cooperative society reduce the bank’s risk.
Step 1: Plan before you approach the bank
Banks look for a realistic plan. Decide:
- How many animals you will start with (starting small, such as 2 to 5 good animals, is often wiser than a large first unit)
- Which breed: cows, buffaloes or both, based on your local market and fodder
- Fodder supply: land for green fodder, or a reliable source to buy
- Who will buy the milk: a cooperative society, private dairy or direct customers
- Who will manage the animals day to day
Get practical training if you are new, for example from a Krishi Vigyan Kendra, state veterinary university or dairy cooperative.
Step 2: Prepare a project report
A detailed project report (DPR) explains your plan in numbers. It usually includes:
- Cost of animals, shed, equipment and insurance
- Monthly costs for feed, fodder, medicines, labour and electricity
- Expected milk yield and income
- Your own contribution (margin money) and the loan amount
- A repayment plan showing you can pay the instalments
NABARD and many banks publish model dairy project reports with typical costs for your region. Your bank's agriculture officer or the district animal husbandry office can guide you.
Worked example: a 5-buffalo unit
The figures below are illustrative only, to show how the numbers fit together. Replace every figure with local quotations and milk prices before you go to a bank.
| Item | Illustrative cost |
|---|---|
| 5 Murrah or graded buffaloes in early lactation at about ₹1,00,000 each | ₹5,00,000 |
| Shed with feeding trough, water and drainage | ₹1,50,000 |
| Chaff cutter and small equipment | ₹40,000 |
| First-year insurance (about 4% of animal value) | ₹20,000 |
| Working capital for about 2 months of feed | ₹60,000 |
| Total project cost | ₹7,70,000 |
| Monthly cash flow (average over the year) | Illustrative amount |
|---|---|
| Milk: about 32 litres a day on average (allowing for dry periods) at ₹50 per litre | ₹48,000 |
| Feed and fodder (about ₹200 per animal per day on average) | −₹30,000 |
| Veterinary care, minerals, electricity, miscellaneous | −₹3,000 |
| Surplus before loan instalment | ₹15,000 |
| Instalment on a ₹6.5 lakh loan at about 9% over 5 years | −₹13,500 |
| Left for the family | about ₹1,500 |
The example shows why many small dairy loans struggle: the margin is thin, and a single dry animal, a case of mastitis or a rise in fodder prices can wipe it out. Ways to improve it include growing your own green fodder, buying higher-yielding animals, a longer repayment period or a moratorium during the first months, family labour, and selling some milk at a better price through a cooperative or direct to homes.
Step 3: Documents usually needed
- Aadhaar card, PAN card and photographs
- Proof of address
- Bank statements and existing loan details, if any
- Land records or a lease agreement for the shed site
- The project report
- Quotations for animals, shed construction and equipment
- Training or experience certificate, if available
- Milk society membership or a letter from a milk buyer, if available
- Caste certificate where applicable for special category benefits
Step 4: Apply and follow up
- Visit a bank branch that handles agriculture loans, a regional rural bank or a cooperative bank
- Discuss your plan with the agriculture officer
- Submit the application with the project report and documents
- The bank may visit your site and check your plan
- On sanction, the loan is usually released in stages, for example for the shed first and then for buying animals
Step 5: Insure and tag your animals
Banks usually require animals bought with a loan to be insured and ear-tagged. Keep policy papers safe. Read our guides on animal registration and ear tags and avoiding insurance claim rejection.
Why dairy loans go bad, and how to prevent it
| Problem | Prevention |
|---|---|
| Animals bought in late lactation or not pregnant | Buy in early lactation; insist on a pregnancy check for animals sold as pregnant |
| Long calving interval (over 15 months) | Detect heat carefully, inseminate on time, check pregnancy at 2 to 3 months |
| Mastitis and udder damage | Clean milking, teat dip, CMT testing, early treatment |
| Fodder shortage in summer | Grow fodder, make silage or hay, budget for buying fodder |
| Calf deaths | Colostrum within the first hour, deworming, clean dry shed |
| Diseases such as FMD, LSD and HS | Vaccinate on schedule; most of these vaccines are free |
Tips to improve your chances
- Start with a modest, realistic unit
- Show a reliable fodder source and a milk buyer
- Keep your bank account active and your credit record clean
- Bring your own contribution ready
- Buy healthy, good-yielding animals from reliable sources, ideally with records
🩺 Dr. Vaishnavi’s Clinical Picks (Available on Amazon India)
Helpful resources and equipment while you plan and set up your farm.
Practical guide for planning and running a dairy farm
Soft, non-slip flooring that protects knees and hooves
As an Amazon Associate, I earn from qualifying purchases. This costs you nothing extra.
Dr. Vaishnavi’s advice: When farmers ask me about a dairy loan, I ask them to do the numbers honestly, including dry months and calf care. Buy fewer but better animals, check them with a vet before paying, and grow your own fodder if you can. A realistic plan is easier to repay than an ambitious one.
Frequently asked questions
Is there a government subsidy for starting a small dairy?
The old NABARD dairy subsidy scheme (DEDS) has ended. Today, farmers mainly use bank loans with KCC interest benefits, state schemes, and support for breeding under the Rashtriya Gokul Mission. Read our DEDS guide.
Do I need land to get a dairy loan?
You need a site for the shed, which can be owned or leased. Many banks also look at your fodder arrangements.
How many animals should I start with?
Many experts suggest starting with a small unit of 2 to 5 good animals, learning, and then expanding.
Can I get a dairy loan without collateral?
Under RBI rules, agricultural and allied loans up to Rs 2 lakh (1 lakh = 100,000 rupees) can be given without collateral. Larger loans may need security.
Recommended reading
- Dr. Vaishnavi’s animal-care books are available on her Amazon author page.
- See all titles on the Books page.
Related Articles
- Dairy Farm Loans and Subsidies in India: Gokul Mission and AHIDF
- AHIDF Scheme: 3% Interest Subvention for Dairy and Feed Plants
- Is the NABARD Dairy Subsidy (DEDS) Still Available?
- Kisan Credit Card for Dairy and Animal Husbandry: Limit and Interest
References
- NABARD. Model bank-financed projects: dairy farming.
- Reserve Bank of India. Master Direction: Kisan Credit Card (KCC) Scheme.
- NABARD. Dairy Entrepreneurship Development Scheme (DEDS): operational guidelines.
More on Government Schemes
NLM Poultry Farming Subsidy: ₹25 Lakh for a 1,000-Bird Parent Unit
Planning a hatchery? Check the NLM poultry farming subsidy 25 lakh eligibility and project report for a 1,000-bird parent farm & mother…
AHIDF Scheme: 3% Interest Subvention for Dairy and Feed Plants
Scaling your dairy business? Learn how the AHIDF scheme gives 3% interest subvention and a credit guarantee for dairy processing and cattle…